



August 26, 2026
ChecklistsWhat Insurance Does a Property Management Company Need? The 2026 Checklist
The 2026 property management insurance checklist: GL, E&O, fidelity bond, cyber, and workers comp, with premium ranges by door count.
15 min read
Loading...
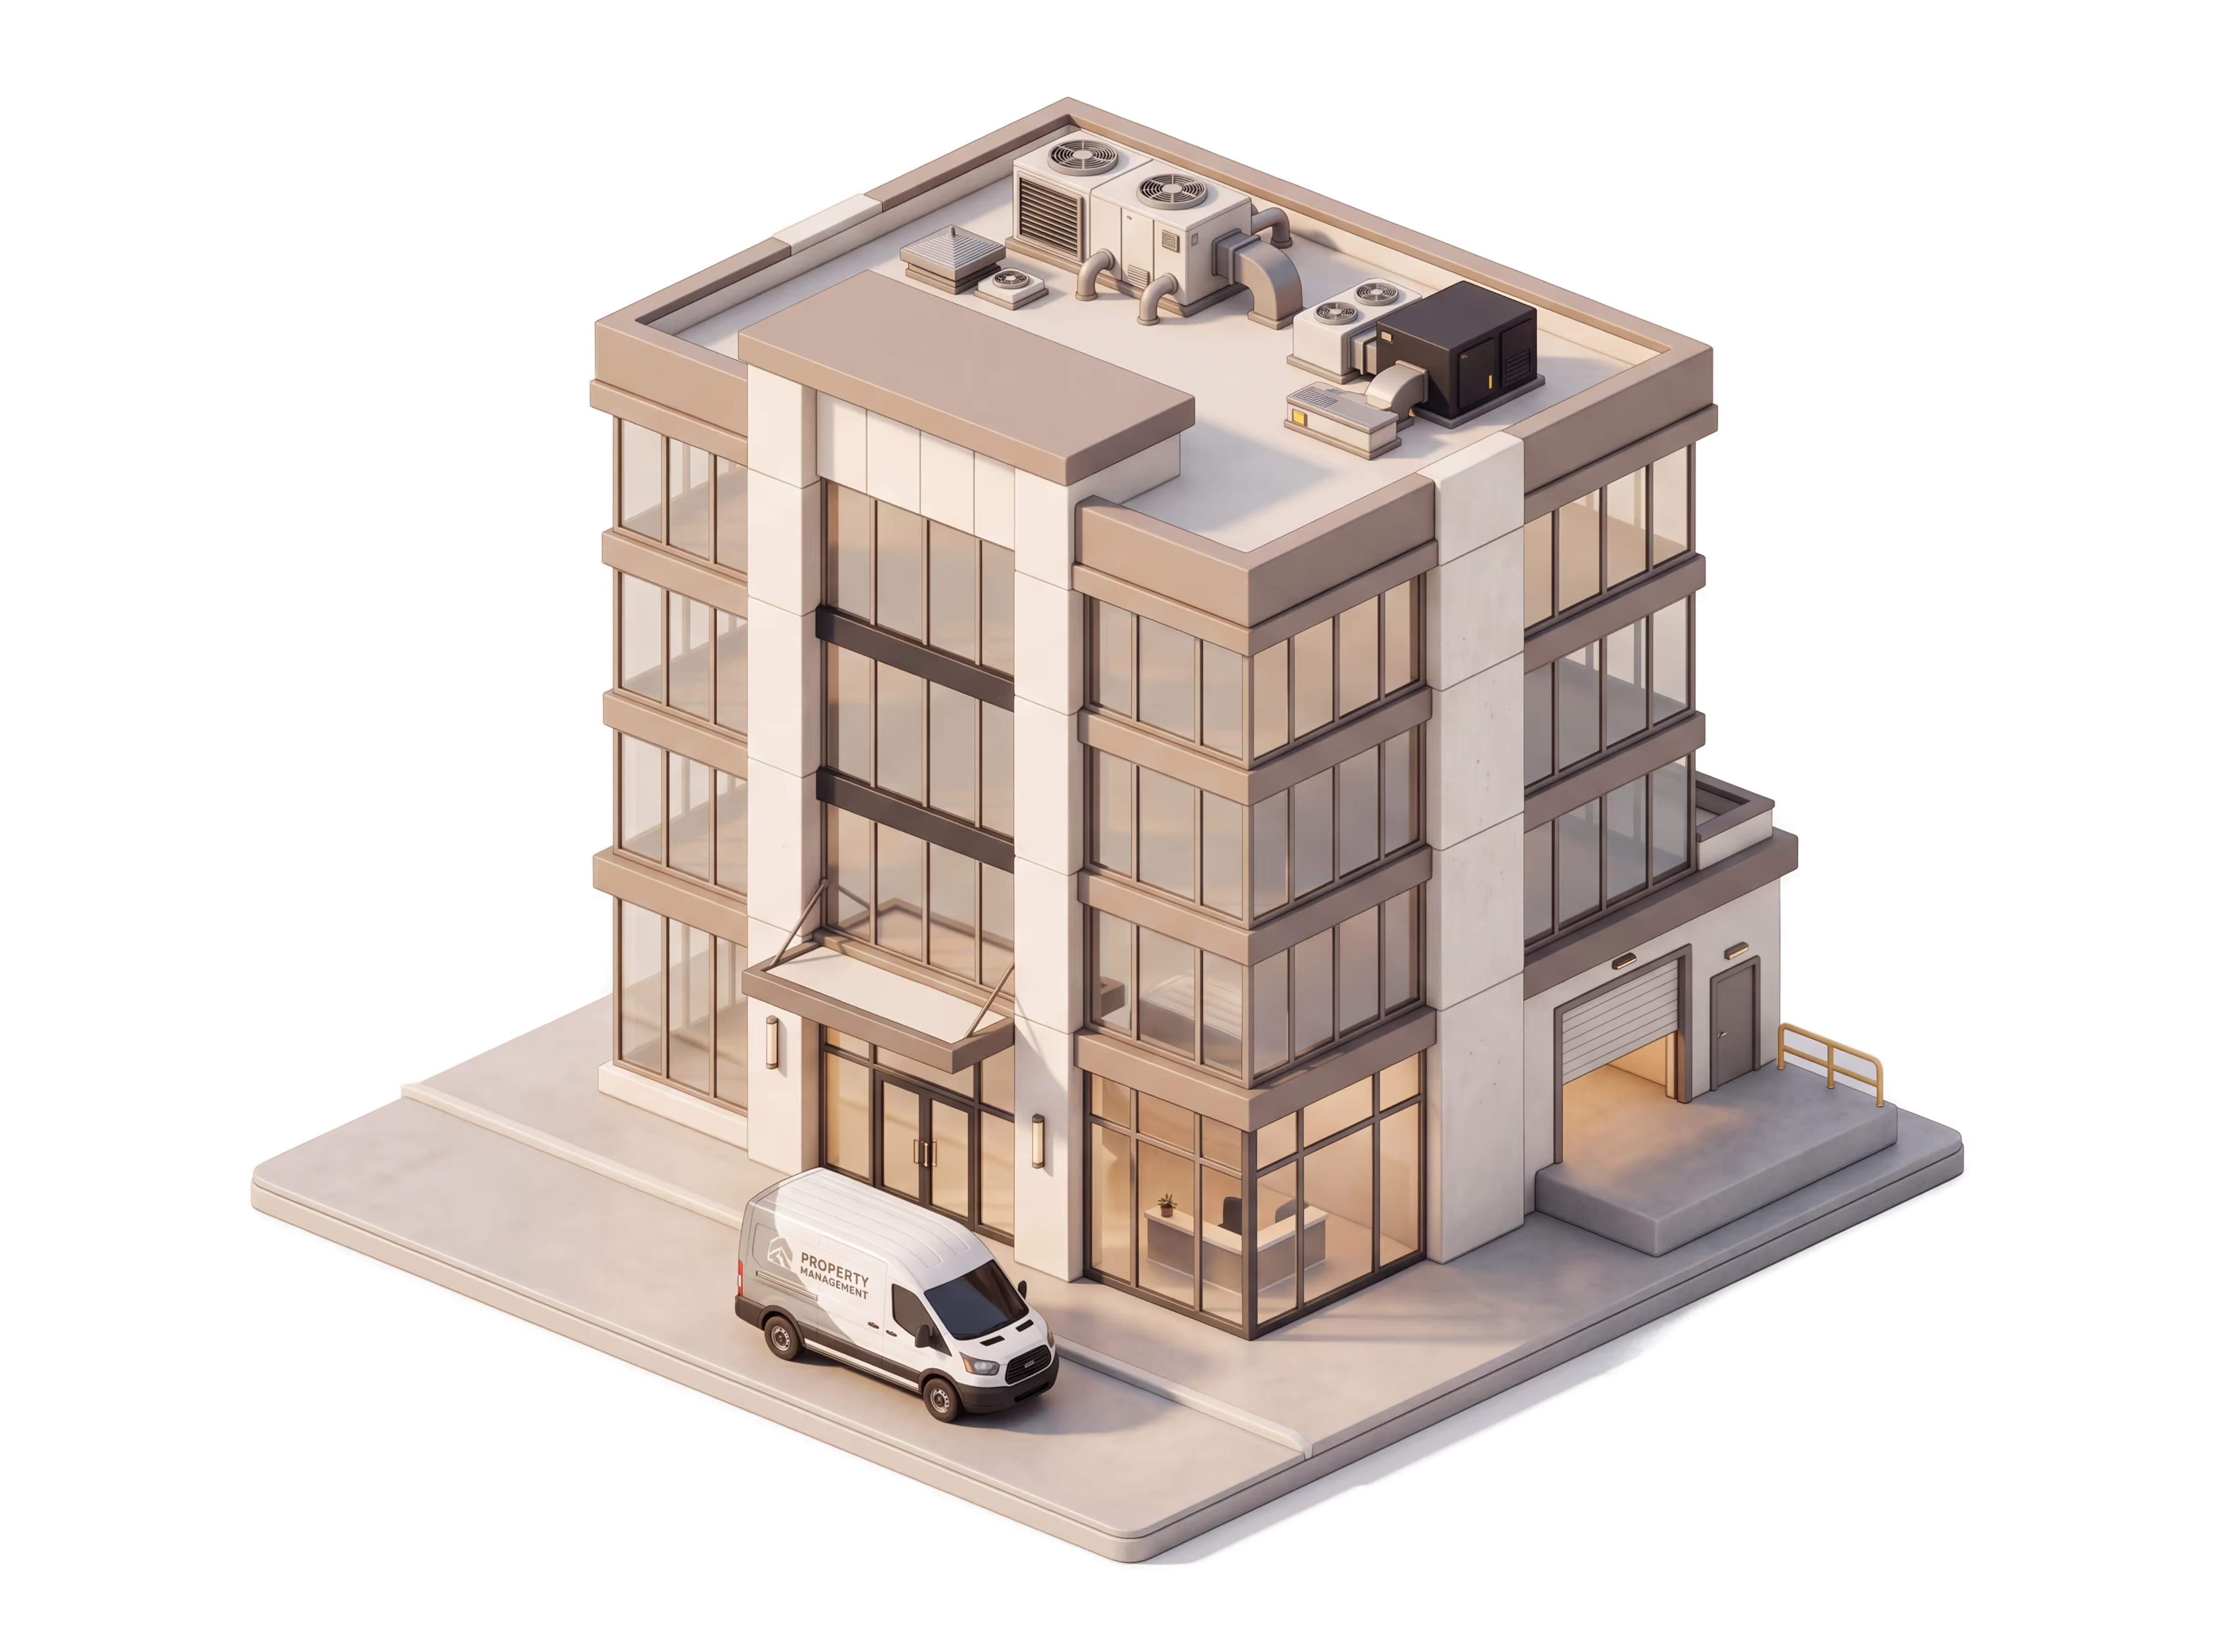
Your E&O limits need to reflect the asset values you oversee. Management fee revenue alone understates the exposure, and residential programs leave the gaps that cost the most.
Trusted by 60+ carrier partners





Commercial property management companies need general liability, professional liability (E&O), workers compensation, and an umbrella policy at minimum.
Add fidelity bonds for operating fund custody, environmental liability for older buildings, and cyber coverage for tenant data systems. The exact program depends on portfolio size, property types, and what your management agreements require.
Updated
Commercial property management insurance is the bundle of policies a commercial PM company carries to cover its operations and professional services. The liability from overseeing office buildings, retail centers, and industrial properties is different from residential work, and standard residential programs are not built for the environmental claims and fund-custody losses that commercial portfolios generate.

Carriers price E&O and umbrella limits against the total asset value under management. A company managing a single strip mall underwrites differently than one overseeing a portfolio of Class A office towers, even at similar management fee revenue.
The number of commercial tenants, the ratio of NNN to gross leases, and the complexity of CAM reconciliation calculations all factor into E&O underwriting. Higher tenant counts and more CAM pass-through categories increase the probability of a calculation dispute.

Three to five years of loss runs and the resulting workers comp experience modifier shape both comp and GL pricing. Prior E&O claims from CAM disputes or lease administration errors narrow the admitted carrier market and increase deductibles.

34% below renewal
“Coverwatch came in 34% below the renewal we were quoted, and every line got better at the same time. Our E&O deductible dropped 80% and our coverage improved significantly. They function as our risk management team, not just our broker.”
Jonathan Sukhia
Co-Founder & CEO · Topkey
Your broker's incentives stay aligned with yours
Commission brokers earn more when your premium goes up. A flat fee removes that conflict. You pay a fixed advisory fee, and every dollar saved on premium stays in your operating budget.
Specialty real estate programs, not generalist markets
Generalist carriers struggle to underwrite E&O, environmental, and fidelity together for commercial PM. Specialty real estate programs price them correctly because they write these accounts daily.
Updated as buildings come and go
Tenant improvement projects add new exposures, and seasonal maintenance hires change your payroll. Your insurance program gets updated as contracts change, throughout the year.
Real exposures your broker should understand and have a plan for.

Lobbies, parking garages, and loading docks at commercial properties see heavy foot traffic. A wet floor in a lobby or an icy walkway at a retail center creates premises liability that flows directly to the management company responsible for safe conditions.
CAM reconciliation is one of the most litigated areas of commercial property management. Errors in calculations and improper pass-through of capital expenses trigger tenant disputes. Multi-tenant disputes compound legal costs quickly.

Older commercial buildings may contain asbestos, lead paint, or underground storage tanks. Tenant improvement projects that disturb contaminants trigger remediation liability and regulatory penalties. Federal regulations require an asbestos inspection before any commercial renovation regardless of building age.

HVAC failure in a data center tenant space, elevator outage in a Class A office tower, or fire suppression malfunction at a warehouse can shut down tenant operations. When the management company maintains the building systems, lost revenue claims follow deferred maintenance decisions.

Commercial property managers handle large operating fund balances across CAM collections, operating budgets, and capital reserves. Employees with access to banking and accounting systems can divert funds for months before an audit catches the discrepancy.

Commercial properties open to the public must comply with ADA accessibility standards. Management agreements often assign common area compliance to the PM, making the company a named defendant when accessibility barriers exist.
Coverage matched to commercial property management exposures.
Get a quote
Required by virtually every management agreement.

CAM disputes and lease errors generate the most claims in commercial PM. Non-negotiable from day one.

Mandatory in most states once you have maintenance or janitorial staff on payroll.

Institutional owners and REITs routinely require umbrella limits above standard GL thresholds as a management agreement condition.

Operating fund custody creates theft exposure that grows with portfolio size. Most institutional contracts set a minimum bond amount.

Standard once staff travel between managed buildings for inspections and maintenance.
Pre-1980 buildings or properties with known contaminants. GL's pollution exclusion leaves no fallback when it applies.

Relevant once tenant data, building automation, or payment systems create a breach notification obligation.

Your own office and equipment. The buildings you manage are insured by their owners.

Optional building coverage for owners and managed portfolios in seismic regions, written separately from the manager’s operating policies.
Need coverage not listed here? Let's talk about your specific exposures.
The licenses, endorsements, and proofs buyers and regulators want to see before they let you on the job.
One platform for a different insurance experience, from quote to claim.
Send your current dec pages, loss runs, and management contracts. We review every policy for gaps specific to commercial property management, with a focus on whether limits match the asset values you oversee.
The limits, mandates, and policy mechanics that show up when a commercial property management company gets underwritten or signs a management agreement with an institutional owner.
A significant share of commercial CAM statements contain material errors according to lease audit firms. CAM reconciliation disputes are one of the highest-frequency sources of E&O claims for commercial property management companies.
Colorado requires E&O insurance for all active real estate licensees, including property managers, at these minimum limits. Roughly 15 states mandate E&O for licensees, but most commercial management agreements require it regardless.
REITs and institutional property owners routinely require commercial PM companies to carry GL with aggregate limits above standard thresholds, plus primary and noncontributory additional insured status and waiver of subrogation.
EPA NESHAP (40 CFR 61.145) requires an asbestos inspection before any commercial renovation or demolition regardless of building age. Management companies authorizing work without a survey face remediation liability and regulatory fines.
Professional liability for commercial property managers is written on a claims-made basis, meaning the policy in force when the claim is reported must cover the error. Tail coverage or extended reporting period endorsements are critical at renewal or program change.
Most institutional management agreements require the PM's GL to name the property owner as additional insured on a primary and noncontributory basis. This ensures the PM's policy responds first before the owner's policy is triggered.
At minimum, general liability, professional liability (E&O), and workers compensation. Most commercial PM companies also need umbrella for multi-building exposures, fidelity bonds for operating fund custody, and environmental liability for older buildings. Cyber and commercial auto round out a typical program.
Yes. Lease administration, CAM reconciliation, and tenant improvement oversight all generate professional liability claims. Audit industry data shows material errors in a large share of commercial CAM statements. Colorado mandates E&O for licensees, and most commercial management agreements require it regardless of state law.
E&O must address CAM reconciliation and lease administration complexity that residential programs skip. Liability limits run higher because commercial properties generate larger claims from tenant business interruption. Environmental and cyber coverage are standard additions for commercial portfolios but rarely needed on the residential side.
E&O responds to claims from CAM reconciliation mistakes, lease administration failures, tenant improvement budget overruns, missed certificate deadlines, and building maintenance decisions that cause tenant damage. GL does not cover management service errors, so E&O picks up where GL stops.
Any commercial PM managing older buildings or industrial properties should carry it. GL's absolute pollution exclusion bars asbestos, lead paint, and underground storage tank claims. The fungi/bacteria exclusion separately bars mold. Federal regulations require an asbestos inspection before any commercial renovation regardless of building age.
The property owner carries building insurance for the structure, common areas, and rental income loss. The management company carries GL, E&O, workers comp, and umbrella for its own operations. Most management agreements require mutual additional insured endorsements on a primary and noncontributory basis.
A fidelity bond or crime policy covers losses when an employee steals operating funds, CAM collections, or capital reserves. Institutional owners and REITs frequently specify minimum bond amounts in the management agreement. Bond limits should match the maximum funds under your control at any point during the year.
CAM reconciliation allocates shared expenses across tenants by square footage, applies lease-specific caps, and separates operating costs from capital improvements. Errors in any step trigger tenant disputes. When one tenant audits and finds systematic overcharges, the remaining tenants in that property typically follow with their own audits.
$41,500 saved annually
Kevin was great. He walked our board through all three quotes, answered every question, and made the whole thing easy. We saved $41,500 on the renewal.
Renewal increase cut to 8%
The renewal for our condo policy came in 28% higher with worse coverage. Coverwatch found the errors in our appraisal and got the increase down to 8%. They explained everything in plain English so the board knew what we were buying.
$10k+ saved on GL
Coverwatch is one of those – why didn't I think of that companies. I hate the last minute take-it-or-leave-it quotes that our insurance agents always did. Coverwatch leveraged AI to put out a much more detailed RFQ that actually listened to the nuances of our business. And more importantly, it got to more carriers and actually made them bid more aggressively for our business. We saved over $10,000 on our general policy alone, and it was a much much better policy with broader coverage. And I actually knew what I was getting for once. Their side-by-side analysis stopped all the guessing of whether the carrier was reputable and what was included. And the brokers fees aren't buried somewhere in the legal language, so there's no surprises. I gave them all our insurance business and have been banging down their door to include health insurance also. Hopefully soon. Can't recommend Coverwatch enough, and I do wish I had thought of it.
Bound in 72 hours
We were three days from a partnership deadline, and insurance was the last thing standing. I had four brokers working on it - Coverwatch went from our first call to fully bound in 72 hours, at the best price of the four. But what actually made them our broker for good was the quote email: it listed the exact risks that were covered so I understood how the policies function, and what each would cost to close. Since then they've acted as our risk management team, not just our policy vendor - proactive, same-day, and straight with us about every tradeoff. Swift turn around with thoughtful suggestion to a change of requirement in less than 24 hours.
Closed an enterprise deal
As a Fintech startup, it's very hard to find affordable insurance that has the coverage we need for our complex business. Kevin helped us navigate the complexity and cross-compare General Liability Insurance that I was unable to do on my own through all these online business insurance vendors. He was able to quickly get us affordable insurance to protect our business so that we could sign a new enterprise client.
Global program placed
Coverwatch took the time to deeply understand our international business before quoting anything: how we operate, where the real exposures are, what our clients expect from us. Then they helped us design a risk plan, with professional liability, crime and cyber working together, and placed coverage that genuinely meets all of our worldwide needs with strong carriers. Responsive, thorough, and truly advisory.
Bound when others passed
Roofing is one of the hardest classes in insurance, and other markets would not touch us. Coverwatch got both our liability and our workers comp bound, on terms that actually cover the work my crews do. Responsive, straight-talking, and relentless. They got it done when nobody else would.
17% lower total premium
Coverwatch caught that our liquor liability didn't cover our off-site catering. They fixed it and still cut our total premium 17%. Easy to work with from start to finish.
Cyber, bound fast
Coverwatch got our cyber coverage right: the limits our customers actually ask about, at a sensible price, bound fast. They took the time to understand what we do, answered every question in plain English, and have been clear and responsive ever since. Simple, quick, and done properly the first time.
One coordinated renewal
Two brokers told us they couldn't help because we're roofers. Coverwatch took the time to understand what our crews actually do, found an insurer that would take us, and put all our policies on one renewal. Straight with us the whole way.
Five stores, one program
Each of our five stores had its own policy. Coverwatch was able to put everything on one program, made sure refrigeration and spoilage were covered at every store, and made adding a new location simple.
A fair price for a new business
Starting a small product business, I found the insurance market overwhelming and most quotes were priced way above what made sense for my size. Coverwatch gave me a fair price based on where I actually am as a new business, communicated clearly, and made the whole process quick and easy. Highly recommend for anyone just starting out.
Covered in days
Fast, fairly priced, and none of the runaround. Coverwatch had us covered in days, explained exactly what we were buying, and they answer in plain English whenever we ask anything. No chasing, no surprises, no jargon. That is all we wanted from a broker, and it is exactly what we got.
46% lower premiums
Kevin and Coverwatch helped us reduce our premiums by 46% and improved our insurance coverage.
Fastest broker we’ve used
Coverwatch is the fastest and most responsive insurance broker I've worked with. They understood our needs and designed an insurance package that was affordable and covered exactly what our business needed.
Send us your policy and a licensed advisor benchmarks your commercial property management insurance across 60+ carrier partners, showing the gaps and the savings. If your program is already solid, we'll tell you.
Your quote
Explore related coverage across the property management space.