
November 12, 2026
ChecklistsRestaurant Deliveries in Personal Cars: Who's Insured?
Review restaurant delivery insurance for employees using personal cars, including driver coverage, return trips, vehicle damage and safe dispatch.
5 min read
Manage your risk with Coverwatch
Get a free coverage review and find out where you are over or under insured.
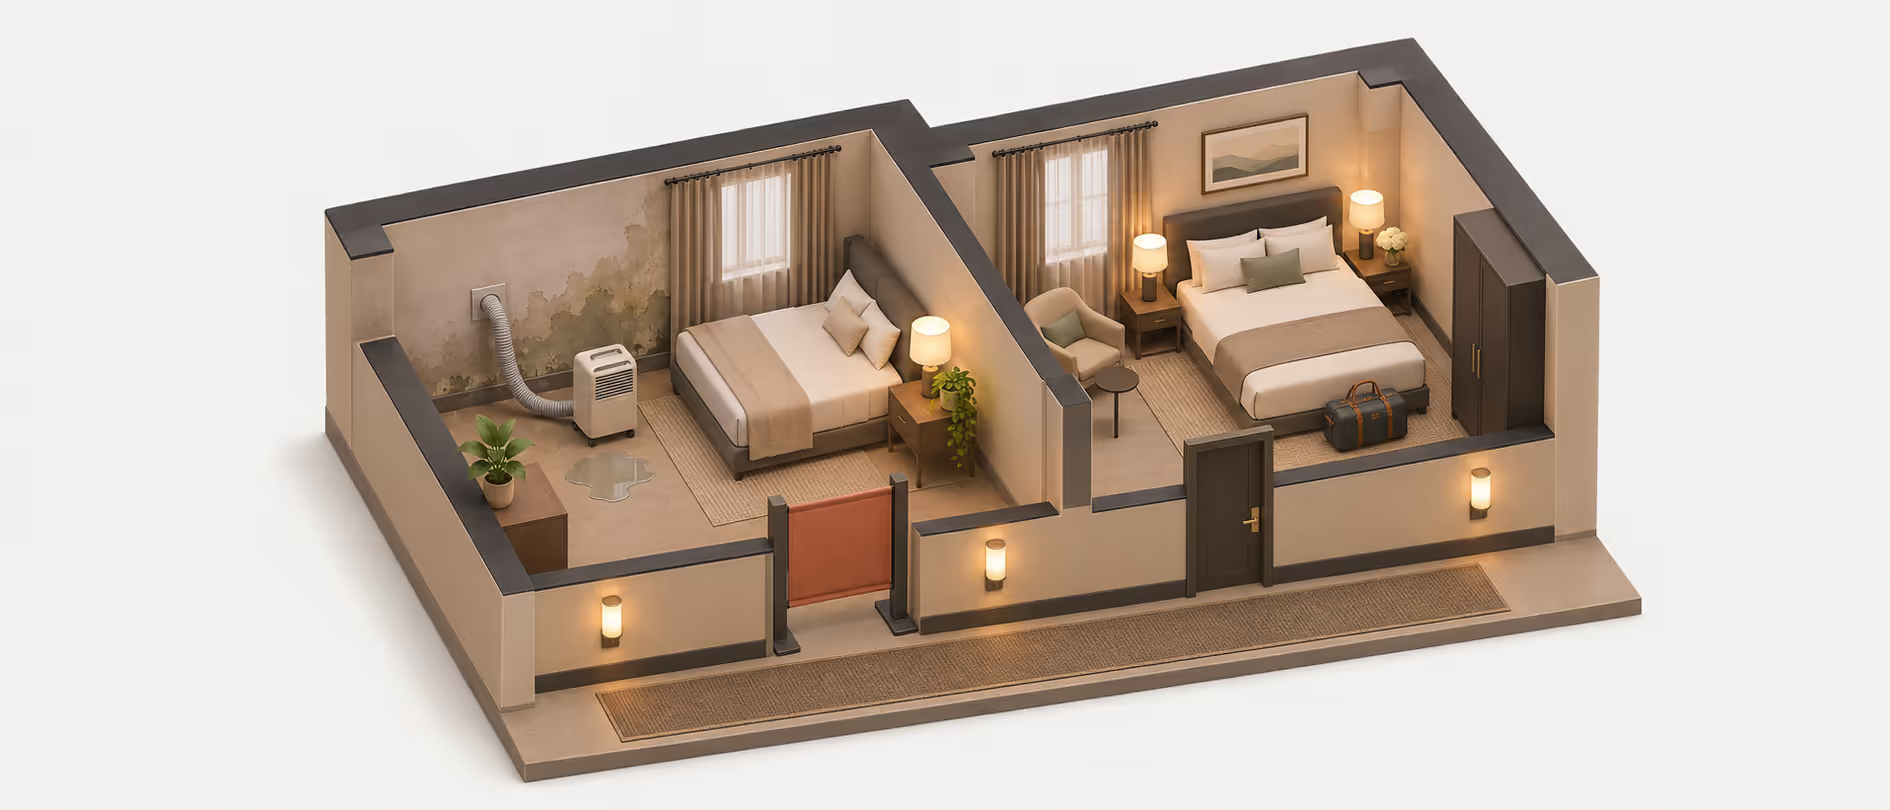
A pipe leak can close guest rooms. Hotel water leak insurance needs to address property repairs and covered income loss separately. The cause, unusable rooms, and applicable policy terms determine how each expense enters the claim.
For an independent hotel, that means organizing one property's repair and revenue records. For a hotel group, it also means showing which location suffered damage and whether guests moved to another hotel in the group. A useful claim file follows rooms and reservations through the interruption, rather than treating every out-of-order room as a lost sale.
Start with the cause of damage. A sudden pipe failure, water entering through a damaged roof, and deterioration around a shower are different facts. The Insurance Information Institute distinguishes covered property damage from excluded causes and maintenance obligations in its property insurance guide. Its examples are illustrative; the hotel's current form and endorsements control.
Ask the broker to separate the damaged pipe or appliance from the damage its escaping water caused. Then ask about the cost of opening walls to reach the problem, drying materials, replacing finishes, and addressing mold if discovered. Do not assume those costs share one coverage answer or one limit. Record each answer against the actual policy wording.
A commercial property review should also identify the building owner, the owner of furniture and equipment, and any lease responsibilities. If mechanical equipment failed, include equipment breakdown coverage in the discussion without assuming that every equipment-related leak qualifies.
Traditional business interruption insurance generally requires covered physical damage and measures covered income loss under its own terms. The National Association of Insurance Commissioners (NAIC)'s business interruption overview explains the distinction between repairing property and replacing net income plus continuing operating expenses. Check the timing rules for when an interruption qualifies and how long restoration can take, alongside the limits and other conditions.
In a hypothetical example, a 60-room hotel removes 12 rooms from service for five nights after a covered water loss. That creates 60 unavailable room nights, but the hotel would not necessarily have sold all 60. Suppose the remaining 48 rooms can absorb every reservation on the first two nights, while demand exceeds usable capacity on the next three. The revenue analysis should reflect that difference.
Build the calculation from the business the hotel reasonably expected to earn, then document what actually happened. Keep cancellations, relocations, replacement bookings, rate differences, and saved expenses separate. A guest who changes rooms and pays the same price is different from a guest who leaves for another hotel. Neither the room count nor the published nightly rate, by itself, establishes the insured loss.
For a group, record transfers between properties and any related reimbursement. Show the adjuster where each reservation ended up. Explain any booking shown as lost revenue at one property and retained revenue at another.
Use a working cost map before combining contractor invoices and guest service expenses. The following categories organize questions; they do not promise that a policy covers each item.
| Cost or loss | Question to put to the insurer | Useful supporting record |
|---|---|---|
| Drywall, flooring, and furniture damage | Which property coverage and valuation terms apply? | Room photos, inventory, repair estimates |
| Failed pipe or worn fitting | Is the failed component covered separately from resulting damage? | Plumber's cause report and retained part |
| Unsold room nights | How will covered income loss be measured? | Reservations, demand history, actual occupancy |
| Temporary measures to keep rooms operating | Can these qualify as extra expense, and is consent needed? | Alternatives considered, receipts, written approval |
| Guest refunds or relocation payments | Which provision, if any, addresses this payment? | Guest ledger and reason for payment |
Agree on coding with the bookkeeper early. An emergency contractor's invoice may contain investigation, mitigation, permanent repairs, and unrelated maintenance. Request enough detail to separate those items. A large invoice labeled only "water remediation" makes it harder to explain the work or compare it with the adjuster's estimate.
Document the damage, notify the insurer promptly, and take reasonable steps to prevent further loss when safe. The Insurance Information Institute's business claim guidance recommends photographs, expense records, and financial documentation. The claims contact can confirm deadlines and the hotel's duties to give notice, allow inspection, and submit a formal loss statement.
For each affected room, record when it closed, why it remained unavailable, and when it could safely return to inventory. Separate physical repair delays from management decisions, such as extending a room closure to complete an unrelated upgrade. Photograph materials and drying equipment before removal. Keep damaged components when safe and practical.
Keep a parallel reservation log. Include the original room type, expected revenue, actual outcome, and any refund. Add contemporaneous explanations for unusual demand, such as an existing group contract or a local event. Those records are more useful than a later assumption that every night would have sold at the highest advertised rate.
Record reopening milestones with the contractor and operations manager. A room may be physically repaired before it is cleaned, inspected, furnished, and released for sale. Ask how the policy treats those steps instead of assuming the last contractor invoice automatically determines the end of the covered interruption.
Bring the broker a realistic partial-closure scenario at renewal. Identify the hotel, room count, building systems, and any prior leak repairs. Ask for a written explanation of the relevant coverage terms, rather than a general assurance that water damage is included.
Assign responsibility now for the property file, reservation exports, and claims communications. At a small hotel, one manager may own all three. A group should name both a property contact and someone who can reconcile financial records across locations. Managers need a consistent set of records.
Coverwatch can help organize the property and income questions into one coverage review. Bring the current policies, a room inventory, and a sample reservation report so the discussion reflects how the hotel actually operates.
No. The cause, exclusions, maintenance history, and policy wording matter. Ask separately about the failed component and the water damage it caused.
A partial closure can warrant a business income review, but payment depends on the damage trigger and actual covered loss. Document whether other rooms absorbed the bookings.
No. That calculation ignores demand, retained bookings, saved expenses, and the policy definition of income loss. Use reservation and accounting records to build the analysis.
Do not delay necessary safe mitigation. Notify the insurer promptly, document conditions, preserve evidence where practical, and confirm inspection and approval requirements before permanent repairs.
November 12, 2026
ChecklistsReview restaurant delivery insurance for employees using personal cars, including driver coverage, return trips, vehicle damage and safe dispatch.
5 min read
November 11, 2026
ExplainersReview hotel pool liability insurance, hot tub risks, federal drain rules, contractor responsibilities, and the records to keep after an incident.
5 min read
November 10, 2026
ChecklistsReview bar live music insurance before adding DJs, dancing, or later hours. Check disclosures, policy restrictions, and New York's 2026 rule change.
6 min read
November 9, 2026
How-ToPlan restaurant business interruption after a kitchen fire: reopening approvals, lost income, payroll, temporary kitchens and claim records.
5 min read
Fill out the form and a Coverwatch advisor will get back to you within the next hour.
Your quote