
November 12, 2026
ChecklistsRestaurant Deliveries in Personal Cars: Who's Insured?
Review restaurant delivery insurance for employees using personal cars, including driver coverage, return trips, vehicle damage and safe dispatch.
5 min read
Manage your risk with Coverwatch
Get a free coverage review and find out where you are over or under insured.
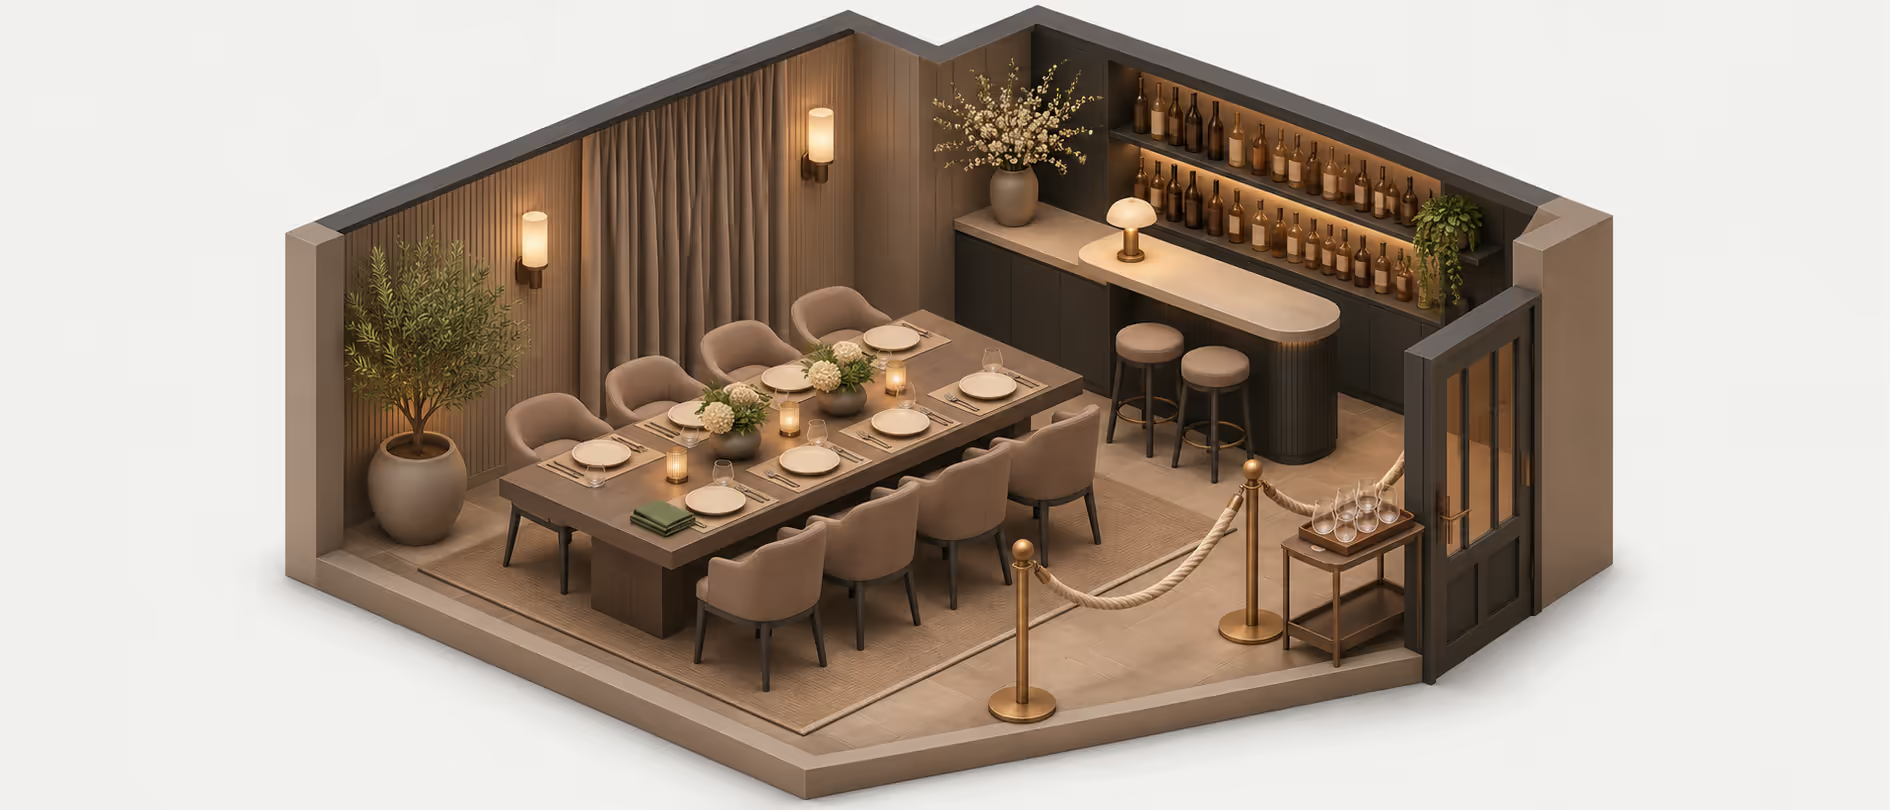
Liquor liability for bar private events still matters when guests drink free. A company buyout leaves the bar in the business of serving alcohol, while the company hosting the party has a separate exposure. Review both parties' policies against who supplies and serves the drinks.
The useful questions are practical: who buys the alcohol, who serves it, who controls admission, and which business could face a claim? Those answers matter more than whether the invitation says private party.
A bar buyout changes the customer arrangement, but it doesn't automatically change the insurance needed for alcohol service. A host's event policy and the bar's liquor liability coverage address different parties. Each policy's definition of the insured business, activities, exclusions, and event restrictions still matters.
IRMI describes host liquor liability as an exposure for parties that aren't conducting alcohol service or distribution as a business. That distinction is about the insured party's activity. It isn't a test of whether an individual guest hands over a credit card.
A bar might collect payment through a room minimum, drink package, ticket arrangement, or final company invoice. Describe that payment structure accurately to the insurer. Don't relabel the service as free to fit a cheaper policy application.
Also confirm that private functions are within the bar's accepted operations. An annual policy may cover the arrangement, require an update, or contain a restriction that needs attention. The event name alone answers none of those questions.
Start with separate coverage checks for the bar and the event host. The bar needs coverage appropriate to its business alcohol service. The host needs to review its own liability for organizing the gathering. Hiring a bartender or requiring a customer policy doesn't automatically transfer every exposure away.
IRMI's liquor coverage guidance identifies bars and other businesses selling, serving, or furnishing alcohol as the intended audience for liquor liability policies. A customer's host-liquor provision should never be assumed to replace that business coverage.
Keep ordinary premises accidents separate in the review. A guest tripping over a loose floorboard raises different coverage questions from an allegation of irresponsible alcohol service. The bar's general liability policy and liquor policy may both need notice when the allegations overlap.
If an outside bartender brings staff, ask which company employs them and whose policy covers their work at this address. A certificate for a different business, or for planning services only, doesn't resolve the server's role.
The event agreement should describe the work each party will actually perform. Use the agreement to identify alcohol service, admission, staffing, and insurance responsibilities before collecting certificates. Then compare those promises with the policy documents. A promise to buy coverage and the coverage actually obtained are separate things.
| Arrangement | Question to resolve | Document to request |
|---|---|---|
| Bar supplies drinks and staff | Does its policy accept this private function? | Liquor policy and relevant endorsements |
| Customer hires an outside bartender | Who supplies, serves, and supervises alcohol? | Vendor agreement and insurance evidence |
| Host rents the room only | Which activities remain under the bar's control? | Rental agreement and host event policy |
| Event uses a patio or separate room | Is that space within the insured operation? | Location information and written insurer response |
Have counsel review indemnity language, meaning contractual promises about paying another party's losses. The broker should review the insurance provisions. Neither review should assume the other has happened.
For a private-event coverage review, an accurate event description is more useful than a broad request for full coverage. Include expected attendance, service hours, entertainment, and any change from normal operations.
Consider a hypothetical company party for 90 guests. The employer pays a $6,000 room-and-drinks package, and the bar's employees serve everyone. Guests don't pay at the counter. The package includes the venue, drinks, and staff for the evening.
The bar should disclose that it supplies the alcohol and service as part of a paid package. The employer should ask its own broker about hosting the party. Those are two separate submissions, even though both relate to the same evening.
Now change one fact: the employer hires an outside bartender who brings alcohol. The contract and coverage review must follow that change. Check the vendor's accepted work, the bar's retained responsibilities, and whether either policy limits outside alcohol service.
Finally, suppose the booking moves to a rented rooftop nearby. The original address and premises assumptions may no longer work. Tell both brokers before the move. A familiar event name doesn't make a new location or operating arrangement identical to the original submission.
Check the party, event, dates, and insurance being evidenced before filing an event certificate. If the bar needs protection under the customer's policy, inspect the actual provision granting that status. A line listing a policy limit doesn't answer which businesses, activities, or allegations the policy covers.
The National Association of Insurance Commissioners' event insurance guide distinguishes liability coverage from cancellation coverage and discusses venues requesting additional-insured status. Its guidance doesn't mean every event product accepts a commercial bar or every host-liquor option covers paid alcohol service.
Resolve mismatches with the broker before the booking proceeds under an insurance assumption. Keep the written answers with the agreement so the on-site manager can find them.
A bar group should use a repeatable event intake process while preserving differences between locations. One site's private dining program may be accepted under its policy; another site's rooftop concerts may need a different review. Record the accepted activities and the person authorized to approve a change.
Build a short booking form covering attendance, alcohol supplier, servers, entertainment, service area, and outside vendors. Route unusual answers to the manager responsible for insurance. That gives the broker usable facts without making the sales team interpret exclusions.
Save policy responses alongside the event contract and vendor documents. At renewal, review the calendar of actual events rather than describing every location as an ordinary neighborhood bar. Include activities that became regular during the year.
Coverwatch can compare the event arrangements with the bar's policies and flag questions for the insurer. Bring a recent booking agreement and a real sample of the certificate packet. They provide a concrete starting point for deciding whether the next private event fits the existing coverage.
No. An open bar describes how guests receive drinks, not whether the business is engaged in serving alcohol. Review the bar and host separately.
It may provide some protection if the bar qualifies as an insured under the relevant wording. Its limits, exclusions, and accepted activities still apply.
Do not assume so. The bar may retain premises, supervision, or contractual responsibilities. Review the vendor agreement and both parties’ policies.
No. Cancellation insurance concerns specified financial losses from a disrupted event. Liquor liability concerns covered claims arising from alcohol service.
Follow the policy’s notice requirements and the insurer’s accepted operating description. Ask the broker which events fit that description and which changes need review.
November 12, 2026
ChecklistsReview restaurant delivery insurance for employees using personal cars, including driver coverage, return trips, vehicle damage and safe dispatch.
5 min read
November 11, 2026
ExplainersReview hotel pool liability insurance, hot tub risks, federal drain rules, contractor responsibilities, and the records to keep after an incident.
5 min read
November 10, 2026
ChecklistsReview bar live music insurance before adding DJs, dancing, or later hours. Check disclosures, policy restrictions, and New York's 2026 rule change.
6 min read
November 9, 2026
How-ToPlan restaurant business interruption after a kitchen fire: reopening approvals, lost income, payroll, temporary kitchens and claim records.
5 min read
Fill out the form and a Coverwatch advisor will get back to you within the next hour.
Your quote